
Table of Contents
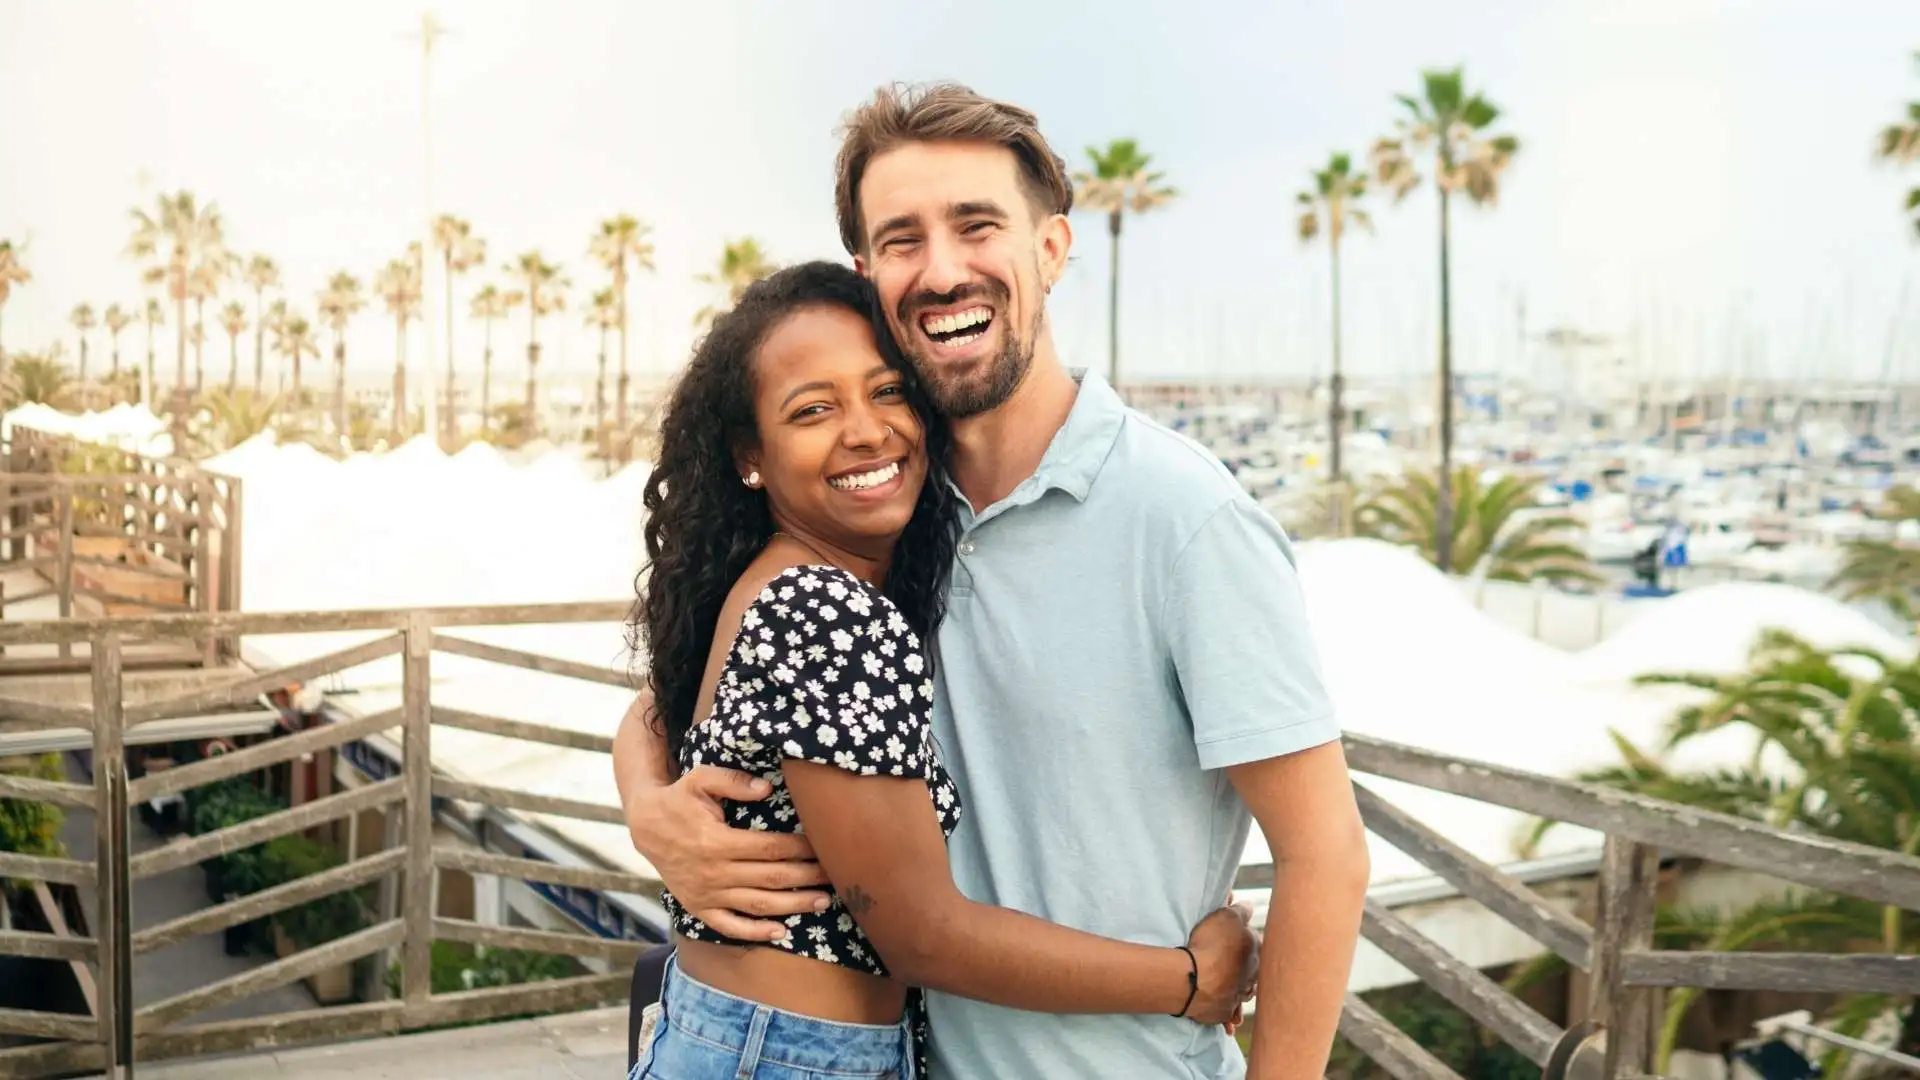
Money disagreements in relationships are rarely about the numbers themselves. They are typically rooted in deeper needs, such as security, freedom, control, and trust. When two people with different money personalities build a life together, spending decisions can quickly feel personal.
One partner may feel safest with structure and savings, while the other may feel constrained by constant caution. Neither perspective is wrong, but without a shared framework, even small decisions can trigger tension.
Most couples do not struggle because they are bad with money or incompatible. They struggle because they are trying to manage shared finances using habits that were formed individually. Intelligent spending offers a more supportive approach.
Instead of forcing one person to change, it focuses on clarity, alignment, and systems that respect both personalities. This allows couples to make decisions together without turning money into a recurring source of conflict.
Understanding Money Personalities in Relationships
Every person enters a relationship carrying a financial history, whether they realize it or not. Childhood experiences, family dynamics, financial stress, and past successes or failures shape these histories.
Someone who grew up with instability may crave savings and predictability, while someone raised in abundance may associate money with enjoyment and ease. These early experiences quietly shape how people respond to spending decisions later.
Problems arise when partners assume their own approach is the correct or responsible one. Labeling a partner as careless, controlling, or irresponsible shuts down meaningful conversation.
Understanding money personalities helps couples move away from judgment and toward empathy. It creates space to recognize that different reactions to money often stem from different experiences, rather than different values.
Common Money Personality Types
Some people feel calm when every dollar has a plan. They prefer structure, predictability, and clear boundaries. Others associate money with flexibility, enjoyment, and freedom, and feel restricted by too many rules. Some prioritize saving above all else, while others avoid conversations about money entirely because they feel overwhelmed or emotionally charged.
Most people are not one extreme or the other. They are a blend of these tendencies that shift depending on circumstances. Recognizing these patterns enables couples to discuss their financial behavior without attacking each other’s character or integrity. When money traits are seen as tendencies rather than flaws, conversations become less defensive and more productive.
Why Opposite Money Styles Often Clash
Opposite money styles clash because they trigger emotional reactions, not logical disagreements. What feels like careful planning to one partner may feel like criticism or control to the other. A saver may interpret spending as recklessness, while a spender may interpret saving as fear-based restriction. These interpretations happen quickly and emotionally.
In most cases, the conflict is not actually about the purchase itself. It is about what the purchase represents. One person may be seeking comfort or freedom, while the other is seeking safety or predictability. Until those emotional drivers are acknowledged, conversations tend to repeat without resolution.
Read: How to Use AI Insights to Decide When to Buy, Upgrade, or Wait
When Conflict Is Really About Safety, Not Spending
For many people, money represents a sense of security. It is protection against uncertainty, emergencies, or loss. For others, money represents freedom and quality of life. When those meanings collide, even small spending decisions can escalate into arguments that feel disproportionate to the situation.
Recognizing what money represents emotionally helps couples reframe conflict. Instead of arguing about transactions, they can talk about needs. This shift allows partners to support each other without invalidating their own comfort levels. Understanding the emotional layer behind spending decisions is often the turning point in healthier financial communication.
What Intelligent Spending Looks Like for Couples
Intelligent spending for couples is not about forcing agreement or changing personalities. It is about creating shared clarity so decisions are not made in isolation. When both partners understand the same financial picture, assumptions decrease, and trust grows. Transparency replaces suspicion, and collaboration replaces conflict.
This approach emphasizes alignment rather than control. It allows differences to exist without destabilizing the relationship. Intelligent spending creates room for individuality while protecting shared stability, making it easier for couples to move forward together.
Shared Visibility Without Micromanagement
Shared visibility does not mean tracking or policing each other’s purchases. It means having a mutual understanding of cash flow, recurring commitments, and shared goals. When visibility is paired with autonomy, it builds trust rather than resentment.
Couples feel safer when surprises are minimized, not when freedom is taken away. Transparency works best when it informs decisions rather than monitors behavior. This balance allows both partners to feel respected and supported.
Creating a Money System That Honors Both Personalities
Healthy relationships rely on systems, not constant negotiation. Without structure, couples often end up debating every purchase, which can quickly become exhausting and frustrating. A clear money system eliminates emotional labor by establishing expectations upfront.
Systems protect the relationship by making decisions easier. They reduce the need for frequent justification and help partners feel secure knowing there is a shared framework in place.
Defining “Ours,” “Yours,” and “Mine”
Many couples benefit from clearly defining shared and personal money. Joint funds typically cover shared expenses, such as housing, utilities, and groceries. Personal spending remains personal, allowing each partner freedom without explanation.
This separation reduces resentment and protects independence, even in committed relationships. Autonomy matters. When personal spending space exists, shared decisions feel less threatening.
Agreeing on Non-Negotiables and Flex Zones
Non-negotiables are the priorities that create safety and stability, such as emergency savings or essential bills. Flex zones are areas where individuality lives, such as hobbies, dining, or discretionary spending. Agreeing on both prevents constant renegotiation.
This clarity reduces emotional exhaustion. Partners know where compromise is expected and where freedom exists, making daily decisions smoother and less charged.
Talking About Money Without Starting a Fight
Money conversations often fail because they occur at the wrong time, typically during stress or after frustration has already built up. Intelligent spending encourages calm, intentional discussions rather than reactive arguments.
Short, regular conversations are more effective than rare, intense ones. When money becomes a normal topic instead of a crisis conversation, tension naturally decreases.
Using Data to Replace Emotion
Spending insights help remove blame from money conversations. Instead of saying, “You always spend too much,” partners can examine patterns together. Data shifts the conversation from accusation to observation.
Facts reduce defensiveness and create a shared reference point. When discussions are grounded in information rather than emotion, solutions feel collaborative rather than imposed.
Building Regular, Low-Stakes Money Check-Ins
Brief check-ins normalize financial conversations. They prevent money from becoming a heavy or avoided topic. Over time, these discussions feel routine rather than stressful.
Low-stakes conversations make it easier to address issues early, before resentment has a chance to build. Money becomes something couples manage together, not something they fear discussing.
Handling Big Differences in Spending Comfort
When one partner feels anxious, and the other feels constrained, compromise must be intentional. Asking both partners to feel equally uncomfortable often solves nothing. Intelligent spending seeks balance rather than symmetry.
The goal is not to meet in the middle on every decision, but to ensure both partners feel respected and secure. Thoughtful systems create room for both comfort and flexibility.
Creating Guilt-Free Spending Allowances
Personal spending allowances remove the need for justification. Each partner has space to spend without explanation or guilt. This autonomy reduces friction and preserves enjoyment.
Clear boundaries protect joy. When personal spending is defined and respected, shared money decisions feel less emotionally charged.
Managing Savings and Goals Together
Savings goals often reflect deeper values. One partner may prioritize long-term security, while the other values experiences and flexibility. Intelligent spending allows both priorities to exist within a shared plan.
Goals work best when they are discussed and agreed upon, not imposed. Shared ownership increases commitment and reduces resistance.
Shared Goals Without Forced Priorities
Emergency funds, travel plans, housing goals, and lifestyle choices are constantly evolving. Flexibility keeps goals relevant and motivating. Revisiting goals together ensures they continue to reflect current needs. When goals feel adaptable rather than rigid, both partners remain engaged. This prevents savings from feeling like a sacrifice and turns it into shared progress.
Read: Intelligent Spending for Subscription Stacks: Streaming, Apps, and Memberships
When Income Levels Are Uneven
Unequal income can quietly influence power dynamics in relationships. Without clarity, resentment or guilt may grow on either side. Intelligent spending addresses this imbalance openly. Fairness does not always mean splitting everything evenly. It means acknowledging capacity, effort, and context.
Fair Does Not Always Mean Equal
Contribution models should reflect what each partner can reasonably provide. Respecting differences preserves dignity and partnership. Equity builds trust more effectively than rigid equality.
Using Tools to Reduce Friction, Not Control Behavior
Financial tools should support alignment, rather than enforcing compliance. Automation reduces emotional labor by handling routine decisions quietly. This prevents repeated arguments over the same issues. When tools work in the background, couples can focus on connection instead of monitoring.
Alerts, Guardrails, and Gentle Signals
Gentle signals prevent surprises without nagging. Alerts, spending thresholds, and reminders help couples stay informed without feeling controlled. These systems protect trust by operating neutrally.
Rebuilding Trust After Money Mistakes
Money mistakes happen in every relationship. Overspending, debt, or miscommunication does not define a partnership. What matters is how couples respond to each other. Repair strengthens relationships when handled with care and consideration.
Repair Over Punishment
Blame creates distance, while repair builds trust. Creating a recovery plan together reinforces partnership. Mistakes become opportunities for alignment rather than sources of shame.
Growing Together as Money Personalities Evolve
Money personalities change over time. Career shifts, parenthood, health events, and life transitions reshape priorities. Intelligent spending evolves with these changes.
Updating Systems as Life Changes
Systems that once worked may create tension later if they are not revisited and updated. Regular updates ensure finances remain supportive instead of restrictive. Flexibility keeps systems relevant and healthy.
Conclusion
Different money personalities do not doom a relationship. When handled with care, they can strengthen it by bringing balance between safety and freedom, structure and flexibility. Intelligent spending creates a bridge between these needs, rather than forcing one to dominate the other.
When couples replace control with clarity and judgment with systems, monebecomesng a source oless f conflict. It becomes a shared tool that supports trust, connection, and long-term partnership. Financial harmony is not about thinking the same way, but about building something that works for both of you.
Over time, these shared systems do more than manage money. They create emotional safety around difficult conversations and reinforce the idea that both partners are working toward the same future. When finances feel supportive instead of stressful, couples gain more space to focus on growth, communication, and life beyond the numbers.
Tools like Beem’s Purchase Intelligence can quietly surface where money is being spent without adding guilt or micromanagement. That awareness helps couples course-correct early, turning gradual improvement into long-term security rather than constant pressure. Download the app now!
FAQs on Intelligent Spending for Couples With Different Money Personalities
Can couples with opposite money habits succeed financially together?
Yes. Success depends on communication, systems, and mutual respect, not identical habits. When couples create shared clarity and agree on boundaries, differences become manageable rather than divisive. Opposite styles often balance each other when supported by the right structure.
How do we avoid controlling each other’s spending?
Create shared visibility and personal spending space. Clear systems reduce the need for monitoring or questioning individual choices. When autonomy is protected, trust grows, and control becomes unnecessary.
Should couples combine all their money?
Not always. Many couples thrive with a mix of shared and personal funds. This approach supports teamwork while preserving independence. The best setup is the one that reduces stress and resentment for both partners.
What if one partner avoids money conversations?
Start small and focus on clarity rather than blame. Low-pressure check-ins build comfort over time and reduce fear around the topic. As conversations become routine, avoidance often fades naturally.
How often should couples review finances together?
Brief monthly or bi-monthly check-ins work well for most couples. Regular conversations prevent issues from building silently. Consistency matters more than length or detail.






