

Table of Contents
A 2023 report by Fidelity revealed that 43% of couples fight about money monthly. Not because they don’t make enough, but because they never developed a system.
Couples usually open a joint account, divide bills, and go their separate ways, and it works for a while until it does not. One person is spending too much on personal stuff, and the other is aware of it, but nobody wants to discuss it over a meal. Managing finances together is more than just paying bills; it is about trust, communication, and a system both people agree on.
That is where micro-budgeting comes in and alters everything.
It is like an envelope system we had in 2025, and there is no need for cash or paper, just a digital system designed to handle rent, bills, groceries, and personal spending in 2026 but with AI. Instead of putting all their money in one account and hoping it balances out, they assign a purpose to every single dollar spent before the month begins.
What Is Micro-Budgeting?
Traditional budgeting provides you with broad categories: rent, groceries, and entertainment. Micro-budgeting takes it a step further. Instead of just knowing what category your money goes into, you know what specific purpose your dollar will serve even before you spend it.
A NerdWallet study found couples who use specific categories to track spending over-spend 23% less than those who use a more general budget. For couples, this makes a big difference. Both people can see exactly where the money is going, which helps eliminate resentment built up when one person feels like the other is spending carelessly.
A couple’s micro-budget might include the following:
- Shared Rent Fund – mortgage or rent, paid out every month
- Utilities Fund – electricity, water, internet bills, no surprise bills
- Groceries Fund – groceries with a hard limit on spending each week
- Savings Fund – an emergency fund or a goal that you are both working towards
- Personal Spending Funds – money that each partner doesn’t need to explain or justify
This last one is more important than most people realize. If each partner has spending money that doesn’t need to be justified to the other person, fights about a $40 takeout meal or a new shirt pretty much cease to exist.
Structuring Shared Accounts Without Losing Control
You don’t have to go all the way with the joint account or the separate account approach; most people who actually do this successfully end up somewhere in the middle.
Shared accounts mean that each person has their own account for discretionary spending, and each person contributes to a shared account for shared spending. If one person makes $80K and the other makes $50K, a 50/50 split can quietly create resentment. A proportional split, where each contributes the same percentage of their income, is a much more peaceful solution.
The key is that the system only works if you set the rules before you need it. Sit down together and talk about it: “What constitutes a shared expense?” “What’s the threshold for a purchase that requires a conversation?” Make it concrete. Couples who do this upfront spend a whole lot fewer minutes arguing about money mid-month.
Also, remember not to “set it and forget it.” Review your contributions every few months or so, especially after a raise, a job change, or a big unexpected expense. What was true in January may not be true in July. The regular conversation prevents small discrepancies from becoming big ones.
Step 1: Define Shared Expenses
Before you spend a single dollar, make a clear definition of “shared” that makes sense to both of you.
For the regular expenses like rent, utilities, food, and insurance, it’s a good idea for both partners to contribute to these without much need for discussion. The harder conversation is about the variable and future spending goals. Does a weekend getaway qualify as a shared expense? A gym membership? Going out for dinner?
Discuss and agree upon these ahead of time and put them in writing. Yes, put it in writing! Couples who put their rules for sharing into writing do not have to discuss money nearly as often because there’s nothing to debate. You can also decide whether to split the money 50/50 or proportionally according to your income and consider a future provision for when your income levels change. Future you will thank the present you for it.
Read: How BudgetGPT Learns from Your Spending Patterns?
Step 2: Set Personal Spending Boundaries
This is where most couples screw it up: They set up their amazing system and then completely forget to account for personal spending.
Everyone should have their own personal spending money. Not as a suggestion, but as a hard and fast rule: A set amount is deposited into their account every month, with no tracking and no need to explain. One person wants craft beer; one person buys too many books. Neither should feel guilty.
The one rule to add: Set a boundary for large personal purchases.
Something like: “If I’m going to spend more than $200, I’ll give you a heads-up before I buy it.”
Not because you need to ask, but because you should tell. And that’s it. That one rule will stop 90% of “You spent how much?” arguments.
Check your limits every few months. Your budget may not be as comfortable as it was when your salaries were last adjusted. Make it flexible so neither person feels controlled.
Step 3: Automate Contributions
The best budgeting system is the one that doesn’t require thought or effort. That’s the beauty of automation.
Automate your deposits into your shared account on the day of your paycheck before either of you has a chance to spend it elsewhere. Automate all your regular bills: rent, utilities, streaming services, and insurance. When money is automatically transferred from your account, no one has to remember to pay the bills on time, remind the other person to do so, or feel responsible in the relationship.
The real benefit of automation isn’t the convenience; it’s the fights it prevents. No one’s sending “Did you pay the electric bill?” texts at 10 pm on a Wednesday. No one feels like the responsible one who’s always managing the finances. The only thing left to do is your monthly check-in once the system is set up.
Micro-Budgeting in the Digital Era
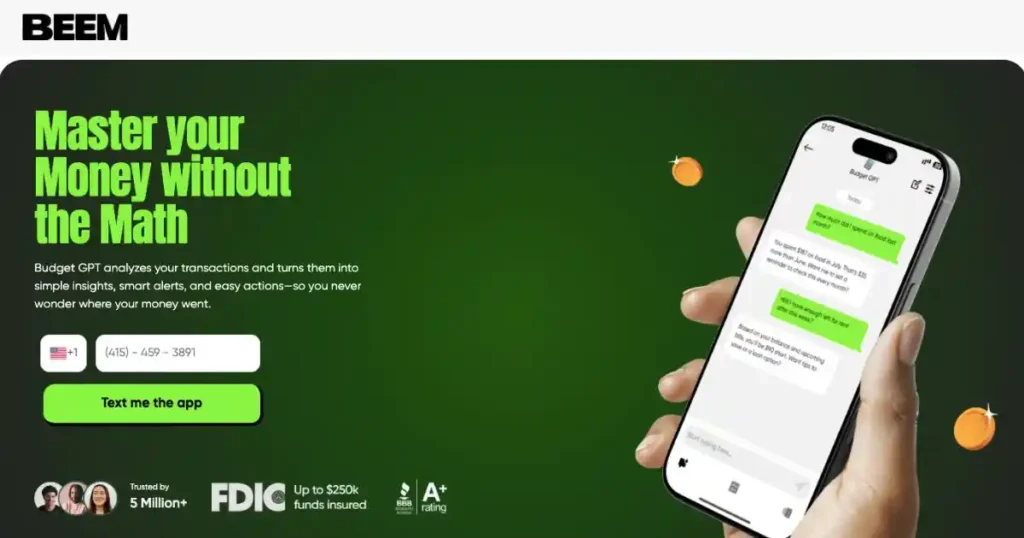
Ten years ago, a shared budget was on a piece of paper, a lot of trust, and at least one awkward conversation about who forgot to log the Costco run. Today, apps like Beem are actually good, and they’re good at making micro-budgeting something couples can actually stick to with ease.
What to use:
Scheduled Bank Transfers: Most major banks offer the option to set up a transfer to take place on a specific date. You can use this to move each partner’s contribution to the shared account on a set date, like every month on payday.
Multiple Savings Buckets: More and more banks are allowing you to have multiple savings buckets within a single user account. You can label them “Rent,” “Groceries,” or “Vacation Fund” in the envelope system digitally.
Expense Tracking: Just connect your accounts, track your spending, and provide each partner with a view of where everything stands at all times. No more manual entry, no more surprises at the end of the month.
Trybeem’s Budget-GPT: This tool analyzes your combined income, determines a fair contribution split, and even lets you see what happens if one partner’s income changes. Less guessing, more clarity.
Micro-Budgeting for Different Scenarios
Not all couples’ financial situations are the same, and microbudgeting can be adjusted to work in a variety of very different situations. Here are some examples: –
When One or Both Partners Run a Business: Income from a business can be unpredictable. A good month may be followed by a bad month. If your budget doesn’t account for these fluctuations, the bad month may cause unnecessary panic. The solution to this is to pay yourself a salary from your business income and put it in your personal account. Your contributions to your shared account are then based on your salary, not your business income. Taxes and business expenses are handled through your business.
When Income Varies Month to Month: If one or both partners are freelancers, contractors, or work on a commission-only salary, a traditional 50/50 split may not work. In these situations, both partners contribute a percentage of what they actually bring home that month. If one partner brings home more, they contribute more. If one partner brings home less, they contribute less. The shared account still gets funded, and neither partner feels penalized for a slow month.
When Both Partners Earn Well: More money does not automatically mean fewer money fights. Instead, it means larger money fights. More money to spend means that micro-budgeting becomes even more important. Pay off joint goals first, then save and invest in goals. Whatever’s left goes into individual accounts. Both partners get financial freedom, but the joint goals do not get quietly sidetracked.
Common Challenges Couples Face in Micro-Budgeting
However, most couples don’t fail micro-budgeting because the system is too complicated. Most couples fail micro-budgeting because of a few very predictable and very fixable mistakes.
Nobody defined what “shared” means: this is the most common mistake. One person assumes that the streaming services are shared, and the other assumes they are not. Nobody ever discussed it either way, and now they are fighting about it. Discuss this ahead of time, make a list of all your expenses, and decide together. Boring? Yes. Worth it? Every time.
All the money goes into one pot: When all the money goes into a single account with no separate buckets, couples don’t see where the money is being spent. One person spends money, and the amount goes down, but the other person has no idea why. Having two or three separate buckets for different things completely changes the equation.
Variable expenses are ignored: Rent is predictable. Repairs, medical bills, holiday gifts, and home maintenance are not. Couples who budget for fixed expenses are often caught off guard every few months by something “unexpected” that was actually completely predictable. A buffer for variable expenses is a great idea, even if it’s just $100 per month. That adds up fast.
Contributions are unequal: A 50/50 split is easy, but what about when one partner makes substantially more than the other? It just becomes a reminder of how much more they earn. A proportional contribution system solves this problem, and more importantly, it eliminates the subtle resentment that comes from feeling like you’re always stretching to keep up.
The budget is never reviewed: A budget you set up in January, based on last year’s income, is not going to work for you in October. Incomes change, expenses change, goals change. A budget review should be scheduled once a month. It should take about 20 minutes. Couples who do this regularly catch little imbalances before they quietly turn into big imbalances.
Money issues in a relationship are seldom about the money; they’re about assumptions that were never discussed out loud. “Fix the communication, and the money problems fix themselves, almost.
How Beem’s BudgetGPT Can Help
Micro-budgeting gives you the structure. Beem gives you the tools to actually run it.
Most couples who struggle with shared finances aren’t bad at math; they’re missing a clear picture of where everything stands. Beem’s BudgetGPT builds that picture for you. It pulls in both partners’ income, breaks everything into micro-budget categories, and suggests a contribution split that’s actually fair based on what each person earns, not just a default 50/50.
It also does something most budgeting conversations skip entirely: it lets you simulate what happens before it happens. One partner’s income drops. A big expense hits unexpectedly. You’re planning a vacation. BudgetGPT models those scenarios so you can adjust your allocations ahead of time instead of scrambling after the fact.
And when something unexpected does hit a car repair, a medical bill, or an expense that didn’t make it into the budget, Beem gives you flexible access to funds without either partner having to raid their personal spending money or blow up the shared account. The joint goals stay on track. The budget stays intact. Nobody has to have an uncomfortable conversation about who’s covering what.
Think of it this way: the budget you build together is the plan. Beem is what keeps the plan running when real life gets in the way.
Final Thoughts
Here’s the truth: no budgeting system fixes a communication problem. But when both partners can see exactly where the money goes and trust that their personal spending won’t be questioned, money stops being the thing you argue about at midnight.
That’s what micro-budgeting actually does. It’s not about tracking every dollar obsessively. It’s about building a system both partners understand, agree on, and don’t have to think about constantly. Shared expenses run automatically. Personal spending stays personal. Goals get funded before either partner has a chance to accidentally derail them.
Beem’s BudgetGPT handles the parts that usually fall through the cracks: fair contribution splits, scenario planning, and goal tracking, so the system runs even when life gets unpredictable.
Set it up once. Tweak it occasionally. And spend a lot less time talking about money in a bad way. Download Beem today from the App Store or Google Play. Staying informed and structured today can make finance management calmer and more predictable.
FAQs
What is micro-budgeting?
Micro-budgeting is a method of breaking down income into smaller, purpose-specific categories. For couples, it helps manage both shared expenses and personal spending while maintaining transparency, control, and fairness. It ensures every dollar has a role and reduces misunderstandings about money.
Should couples combine all their money?
Not necessarily. Many couples use hybrid systems that include both shared and personal accounts. This approach allows joint expenses to be covered efficiently while preserving financial independence for individual discretionary spending, preventing conflicts over personal choices.
How do couples split shared expenses?
Shared expenses can be split equally or proportionally based on each partner’s income. Proportional contributions are particularly useful when incomes differ, ensuring fairness while making it easier to manage recurring bills and joint financial goals.
Can shared accounts cause financial conflict?
Yes, if couples haven’t clearly discussed expectations, spending boundaries, and responsibilities. Without communication, misunderstandings can arise over contributions, discretionary spending, or priorities, making open and regular financial conversations crucial.
Can budgeting tools help couples manage money?
Absolutely. Tools like Beem’s Budget-GPT provide structured planning, track shared and personal goals, simulate financial scenarios, and suggest fair contribution splits. They simplify micro-budgeting, enhance transparency, and reduce stress while helping couples maintain financial balance.






