

Table of Contents
Creating an emergency fund is an essential step towards long-term financial stability, especially for individuals with variable income. Freelancers, gig workers, commission-based professionals, and business owners are some of the individuals with variable income. Without the security of a regular income, one month of low pay can wipe out your entire financial foundation.
According to Bankrate’s annual savings report, only about 46% of people in the United States have saved enough to go three months without earning. This means that more than half of the population is still unprepared for financial emergencies. You must be the well-prepared one.
Experts recommend that an individual save at least three to six months of their monthly expenses for emergencies. This may be an ideal suggestion for those with variable income; however, it’s daunting for many. A more realistic approach is to build a one-month emergency fund and gradually grow it further.
This emergency fund helps the variable-income earner accumulate a good amount of money that acts as a financial cushion against variable income and provides stability in the face of unexpected occurrences.
Why Variable Income Requires a Different Strategy
Let’s understand this with the help of an example:
A salesperson earns a commission-based salary. In January, they made four sales, which translates to a $9,000 paycheck. In February, they got no sales and that translates to a paycheck of $1,800. Their rent, groceries, and electricity bills don’t change just because they made 80% less. This is what happens to millions of people in the United States: freelancers, gig workers, or those who work on a commission-based salary.
With such low-income months, the advice to save 20% of your paycheck doesn’t work. Saving a fixed percentage sounds practical in theory, but in months where income drops sharply, that percentage can become unrealistic or even impossible to maintain.
As a result, a different strategy is necessary. For the same reason, the first step for a variable income earner is to build an emergency fund slowly, but consistently, and, over time, it compounds to a financial cushion for uncertain times.
Step-by-Step Guide to Build An Emergency Fund
Here’s a 4-step guide on how to build an emergency fund when you earn a variable income.
Step 1: Calculate One Month of Essential Expenses
Before you start saving a dollar, you need to know your numbers:
The first step in creating a one-month emergency fund is to determine your essential monthly expenses. An average household in the United States spends between $2,000 and $6,000 per month, which is a significant amount.
These are non-negotiable costs that must be met to maintain basic living conditions. Understanding these expenses clearly helps you determine how much money you need to stay financially stable during an emergency or a temporary income gap.
When income is unpredictable, knowing your minimum required expenses becomes even more important for effective financial planning.
Essential expenses typically include:
- Rent or mortgage payments
- Utilities (electricity, water, internet, phone)
- Insurance premiums (health, auto, home)
- Minimum debt payments
- Basic groceries
- Transportation costs (fuel, public transit)
Avoid including discretionary expenses such as dining out, entertainment subscriptions, or luxury items. Focus on survival-level budgeting.
Ask yourself, if you stopped earning tomorrow, what are the things that cannot go unpaid? By concentrating on core expenses, individuals set a realistic emergency fund target that feels achievable rather than overwhelming.
Tips for calculating essentials:
- Use an average if expenses fluctuate each month.
- Focus only on needs, not wants.
- Keep calculations simple to avoid overcomplicating the target.
This focused approach ensures that your emergency fund provides adequate protection without setting unrealistic savings goals. It also helps people gain confidence in their financial planning, making it easier to save consistently over time.
Step 2: Set a Realistic Savings Timeline
Once the essential expenses are determined, the next step is to set a timeline for saving the target amount. This might not be perfectly predictable for individuals whose income varies, and that’s perfectly fine.
The key here isn’t a deadline but continuous progress. For example, if you make $6,000 one month, set $600 aside; if you make $3,000, bump it to $300.
Here’s what actually works:
- Dividing the target savings into weekly or bi-weekly targets.
- Saving a certain percentage of income rather than a set amount, as this will adjust for variable pay
- Saving as much as possible in months when income is higher
In months when income is lower, adjust savings as much as possible; consistency is key.
Another strategy for achieving this is to think of savings as a continuous process rather than a one-off task. This helps maintain momentum and achieve the target savings. Setting small targets also helps maintain motivation as the savings become visible.
Step 3: Keep the Fund Accessible
If you can’t get the money in 24 hours, it’s not an emergency fund; it’s just savings.
This fund’s primary goal is to provide immediate financial assistance in unexpected situations such as medical bills, urgent repairs, or temporary income loss. If the money is difficult to access or locked up in long-term investments, it may not be available when you need it most. As a result, accessibility has to be a top priority when deciding where to store emergency funds.
Accessibility tips:
- Store funds in a separate savings account.
- Ensure quick withdrawal options without penalties.
- Avoid investing in volatile assets like stocks, as they delay access.
- Liquidity is more important than earning high returns.
Keeping the emergency fund in a separate account also helps to avoid accidental spending. When money is kept separate from everyday accounts, it is easier to maintain discipline and use the funds only in an emergency. A simple or high-yield savings account is often the best option because it offers security, stability, and convenience.
Accessible funds also reduce reliance on high-interest credit cards or loans, allowing you to bridge income gaps confidently. Having immediate access to savings is extremely beneficial during times of financial stress. It provides peace of mind and ensures that unexpected expenses are managed without causing long-term financial burdens or debt.
Additionally, choosing accounts with online and mobile banking features ensures you can access funds anytime, anywhere, further enhancing convenience and readiness during urgent situations without unnecessary delays.
Step 4: Automate Contributions When Possible
Automated systems reduce friction and promote consistent saving habits. By automating the saving process, an individual no longer requires constant reminders or motivation to direct their income into an emergency savings account. As a result, automating increases the likelihood of saving nearly threefold.
Some of the automation techniques that people use include:
- Set the account to transfer income deposits to the savings account automatically.
- Apply percentage-based contributions to accommodate variable income.
- Adjust the amount transferred according to the monthly income received.
Another advantage of the automation technique for developing an emergency savings plan is that it supports the development of financial plans. By automating savings, an individual does not need to remember to set aside some of their income for the emergency account.
The automated approach helps develop financial plans by preventing individuals from spending their income before setting aside some amount in an emergency account. Automation also helps develop financial plans by allowing individuals to direct more income to their savings accounts as income increases.
Consistency reduces decision fatigue and reinforces disciplined saving. Even small, repeated contributions compounds over time, gradually building a meaningful emergency fund. With patience and regular deposits, automated savings steadily grow into a reliable financial safety net that protects against unexpected situations.
Common Mistakes to Avoid
Many variable-income earners unintentionally undermine their emergency fund goals due to common financial habits or planning mistakes.
- One frequent issue is waiting for a stable income before starting to save. Because income variability may continue for long periods, delaying savings leaves individuals unprepared for emergencies.
- Another mistake is using emergency funds for non-essential expenses, which defeats the purpose of having a financial safety net.
- Some people also invest their emergency savings in risky or illiquid assets in search of higher returns. However, emergency funds should remain safe and easily accessible.
- Setting unrealistic savings targets also discourages progress, especially when income fluctuates.
- Additionally, ignoring regular expense tracking makes it harder to understand how much should be saved. Finally, many individuals stop contributing after small setbacks, which slows long-term progress.
Keeping the plan simple, realistic and consistent helps individuals stay consistent and achieve long-term financial stability.
How Trybeem’s BudgetGPT Helps
It’s challenging to keep track of unnecessary expenses and savings goals.
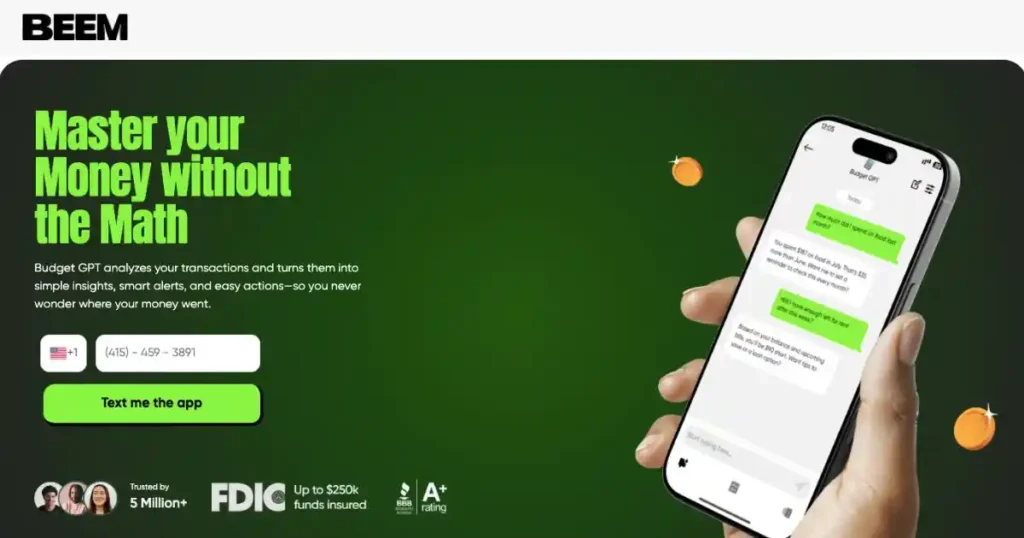
Trybeem’s BudgetGPT makes this process easier. It helps by using income patterns to provide practical advice that makes the financial planning process easier.
Some of the key features of BudgetGPT include:
- Helps you identify a specific savings goal based on your fundamental monthly expenses
- Makes an informed estimate of how much to save based on your actual income patterns
- Helps you save a percentage of your income so that as you earn more, you save more
- Simulates high-and low-income months to ensure that you are prepared for any situation
- Helps you track your emergency fund growth as you hit milestones
- Alerts you when your income changes and helps you adjust your savings accordingly
BudgetGPT provides practical guidance on building an emergency fund by simplifying complex financial concepts into clear, actionable steps that individuals can realistically follow and sustain within their income limits.
Try Beem At The Time Of Unexpected Expenses
Unexpected expenses occur even before a one-month emergency fund is established. Medical bills, unexpected repairs, or unplanned travel expenses may require instant financial support. In such cases, timely support may assist individuals in avoiding debt through credit cards with high interest rates.
Beem is a financial tool that helps individuals meet their short-term needs during difficult financial situations. The flexible access options offered by Trybeem, along with its structured support solutions, enable users to meet their financial needs without compromising their plans. Such financial support is particularly advantageous for individuals with variable income, such as freelancers or gig workers.
When used with smart financial planning tools like BudgetGPT, Beem helps users achieve financial balance. These tools help users meet both their immediate financial needs and long-term financial goals, making it easier to achieve financial balance easily and improve their financial health in the long run.
Financial tools like Beem help users stay consistent with their savings habits during uncertain financial times. Such consistency is essential in gradually building users’ emergency funds.
Final Verdict
A one-month emergency fund is an achievable goal for people with variable incomes. This is a good idea because it helps individuals cover necessary expenses, creating a financial cushion when income is lower than expected.
People with variable incomes can feel confident about their financial situation when they know their necessary expenses, save money, and store it in easily accessible places. The initial goal of saving money, which is building a one-month emergency fund, may grow into a bigger emergency fund in the future, creating a sense of security.
When people are building something new, the best way to get started is from scratch, taking things step by step. Saving money, however small the amount, is a good idea because it helps people build confidence in saving. The better the saving habits, the larger the emergency fund grows, turning the initial goal of saving money into a larger emergency fund.
Download Beem today from the App Store or Google Play. Staying informed and structured today can make finance management calmer and more predictable.
FAQs
1. How much should someone with a variable income save first?
A practical starting point is saving enough to cover one month of essential expenses. This creates a basic financial safety net for emergencies or income gaps. Once this goal is achieved, individuals can gradually build a larger reserve.
2. Is three to six months still necessary?
Yes, financial experts still recommend saving three to six months of expenses for long-term stability. However, variable-income earners can build this gradually once they have secured the first month of savings. Expanding the fund step by step makes the goal more manageable.
3. Where should emergency funds be kept?
Emergency funds should be kept in a safe and easily accessible savings account. The money should be available quickly in case of urgent needs. Avoid accounts with withdrawal restrictions or penalties.
4. Can emergency funds be invested?
Emergency funds generally should not be invested in stocks or other volatile assets. Investments can fluctuate in value and may not be accessible during emergencies. Keeping the fund liquid and low-risk ensures reliability when it is needed most.
5. Can budgeting tools help build emergency savings?
Yes, budgeting tools can make saving easier and more structured. Tools like Trybeem’s Budget-GPT help calculate essential expenses, set realistic savings targets, and track progress. They can also adjust plans based on changing income patterns.






