

Top 10 Credit Builder Apps To Build Credit Safely In 2026
Building credit is one of the most important financial steps you can take. A strong credit profile affects loan approvals, interest rates, rental applications, and even insurance pricing. For many people, however, knowing where to start can feel confusing or intimidating.
Credit builder apps simplify the process. They are designed to help you create positive credit activity through structured payments, smart reporting, and everyday financial habits.
Whether you are starting from scratch or repairing past mistakes, the right credit building app can help you move forward with confidence.
This guide breaks down the best 10 credit builder apps, explains how each one works, and helps you decide which option fits your financial goals.
What Is a Credit Builder App?
A credit builder app is a financial tool designed to help users establish or improve their credit history. Most apps work by reporting on time payments to one or more major credit bureaus. Over time, this positive payment history can lead to a higher credit score.
Unlike traditional credit cards or loans, many credit builder apps are designed to reduce risk. Some use secured funds, others use installment style savings plans, and some report everyday payments like rent or subscriptions.
Common goals of credit builder apps include:
- Creating a consistent payment history
- Helping users avoid missed payments
- Reporting activity to credit bureaus
- Offering visibility into credit progress
How We Chose the Best Credit Builder Apps
To create this list, we focused on apps that meet the following standards:
- Report to at least one major credit bureau
- Offer transparent pricing and clear terms
- Are accessible to people with little or no credit
- Provide real value beyond basic reporting
- Have a track record of positive user feedback
Best 10 Credit Builder Apps To Use In 2026
Below are the top 10 credit builder apps available today, ranked based on effectiveness, usability, and overall value.
1. Beem Credit Builder Card – Best Overall Credit Builder App
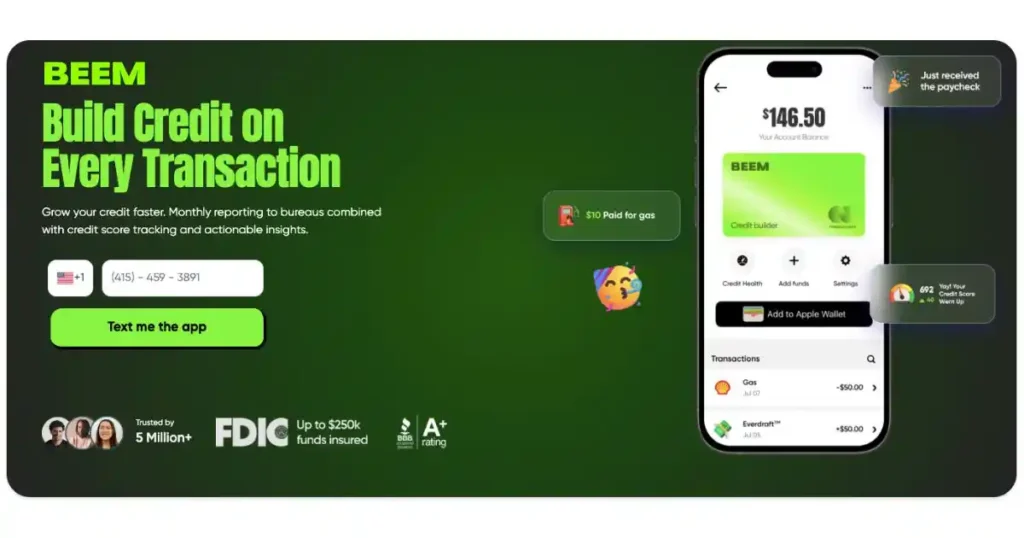
Website URL: https://trybeem.com/credit-builder-card
Beem offers a credit builder card that helps users grow credit through everyday spending. Unlike many secured cards, Beem does not require a traditional security deposit. Instead, it focuses on responsible usage and consistent reporting.
Every on time payment is reported to credit bureaus, helping users build a positive payment history while using the card like a regular debit or credit card.
Features of Beem
- No security deposit required
- Reports payments to major credit bureaus
- Works with Apple Wallet and Google Wallet
- Designed for everyday purchases
- Part of a broader financial ecosystem
Beem is especially useful for people who want a credit builder that fits naturally into daily life rather than feeling like a separate financial obligation.
Beem stands out as the best Credit Builder App for people who want to build credit without changing how they manage everyday spending. Instead of requiring a traditional security deposit like most secured cards, Beem removes that barrier and focuses on responsible usage and consistent reporting.
This makes it easier to get started, especially for users who may not have extra cash set aside.
As a modern Credit Building App in the USA, Beem is designed to work like a regular card you can use for groceries, gas, subscriptions, and daily expenses.
Every on-time payment is reported to the major credit bureaus, helping users establish and strengthen their payment history over time.
Because payment history carries the most weight in credit scoring, this consistent reporting plays a major role in long-term credit growth.
What makes Beem different from many other options is how naturally it fits into daily life. You’re not managing a separate loan or remembering a one-off monthly payment.
Instead, credit building happens as part of your normal spending habits, which makes it easier to stay consistent and avoid missed payments.
Key Benefits of Beem
Beem removes the need for a security deposit, making it more accessible than many traditional credit builder cards. It reports payment activity to major credit bureaus, ensuring your responsible usage actually counts toward your credit profile.
The card works seamlessly with Apple Wallet and Google Wallet, allowing for easy, contactless payments. It’s built for everyday purchases, not occasional use, which helps keep your account active.
Beem is also part of a broader financial ecosystem, giving users access to additional tools that support better money management.
Because of this balance of simplicity and functionality, Beem is often considered the best Credit Builder App for users who want steady, realistic progress without added complexity.
Best For
Beem is ideal for anyone looking for long-term credit growth through simple, real-world usage. If you want a Credit Building App in the USA that feels like a normal spending tool rather than a forced financial task, Beem offers a practical and sustainable approach.
For many users, it’s the best Credit Builder App to start with and grow alongside as their financial habits improve.
2. Self – Build Credit, Build Savings and Access Cash

Self uses a credit builder loan model that combines credit building with forced savings. Instead of receiving money upfront, you make monthly payments that are placed into a locked savings account.
Your payments are reported to credit bureaus, and once the term ends, you receive the savings balance.
How Self Works
- Choose a monthly payment plan
- Make fixed payments each month
- Payments are reported to credit bureaus
- Receive funds at the end of the term
This structure helps users build discipline while strengthening their credit profile.
Build Credit Safely With Self
Self helps users build credit through a Credit Builder Account. You make fixed monthly payments that are reported to all three major credit bureaus—Experian, Equifax, and TransUnion. Regular, on-time payments improve your payment history, which is a key factor in credit score growth.
Build Savings Automatically
Instead of borrowing money upfront, your monthly payments are securely set aside in a savings account. After completing the plan, you receive the saved amount (minus applicable fees). This makes Self a disciplined way to save money while improving credit simultaneously.
Access Cash and Credit Options
Once you establish a positive payment history, Self may offer a secured credit card backed by your savings. This helps improve credit utilization and credit mix. In certain situations, users may also be able to access funds early, providing limited financial flexibility.
Who Is Self Best For?
- Individuals with no credit or poor credit history
- Users who want to build savings while improving credit
- People looking for a low-risk, structured credit-building solution
Key Benefits
- Reports to all three major credit bureaus
- No hard credit check to get started
- Combines credit building and savings
- Transparent monthly payments and terms
Example
A user selects a 12-month plan with fixed monthly payments. Each on-time payment helps improve their credit score, and at the end of the term, the accumulated savings are returned—making Self both a credit-building and savings-focused platform.
Best for: People who prefer predictable payments and a savings outcome.
3. Experian Boost – Best for Instant Credit Improvements

What Is Experian Boost?
Experian Boost is a free service from Experian that helps increase your credit score quickly by adding positive payment history from everyday bills. It works instantly and can benefit users with limited credit profiles.
How It Works
Experian Boost connects to your bank or credit union and scans your transactions for on-time payments of qualifying bills, such as:
- Utility bills (electricity, gas, water)
- Phone bills
- Streaming services (Netflix, Spotify)
When it finds consistent, on-time payments, it adds them to your Experian credit file—potentially boosting your score instantly.
Key Benefits
- Quick results: Many users see a credit score increase immediately after signing up.
- No cost: The service is completely free to use.
- Works with everyday payments: It uses payments you already make regularly.
Who Should Use Experian Boost
- People with limited or thin credit files
- Users looking for instant improvements in credit score
- Individuals who pay bills regularly but aren’t seeing credit score growth
Example
If you pay your phone and utility bills on time every month but haven’t built much traditional credit yet, Experian Boost can add this positive payment behavior to your credit report. This can result in an immediate uptick in your Experian credit score helping you qualify for loans or better interest rates faster.
Tips for Best Results
- Connect all your bank accounts for a more comprehensive review.
- Ensure bill payments are consistently on time.
- Use it alongside traditional credit-building practices for maximum impact.
Experian Boost is a smart, low-effort way to enhance your credit profile using payment history you already have.
Best for: People with limited credit who pay bills consistently.
4. Credit Strong – Best for Long Term Credit Building

What Is Credit Strong?
Credit Strong is a credit-building program designed for users who want to improve their credit score steadily over time. It focuses on long-term credit health by helping build strong payment history, credit mix, and higher account age.
How Credit Strong Works
Credit Strong offers installment-based credit builder accounts where you make fixed monthly payments over a longer duration. These payments are reported to all major credit bureaus, helping establish consistent, positive credit behavior. Some plans also combine savings and credit-building benefits.
Why It’s Ideal for Long Term Credit Growth
- Reports monthly payments to Experian, Equifax, and TransUnion
- Helps build long credit history, which improves credit stability
- Supports credit mix by adding installment accounts
- Encourages disciplined financial habits over time
Who Should Use Credit Strong
- Users focused on long-term credit improvement, not quick fixes
- People with poor or no credit history
- Individuals planning future goals like home loans, auto loans, or business credit
Key Benefits
- No hard credit check to start
- Multiple plan options based on goals
- Helps improve payment history and account age
- Structured and predictable monthly payments
Example
A user enrolls in a 24- or 36-month Credit Strong plan and makes all payments on time. Over time, their credit profile strengthens due to consistent reporting, longer account age, and improved payment history, making them more attractive to lenders.
Credit Strong is best suited for users who are patient, goal-oriented, and serious about building a solid credit foundation for the future.
Best for: Users committed to long term credit improvement.
5. Kikoff – Best Low Cost Entry Level Credit Builder

What Is Kikoff?
Kikoff is a simple credit-building tool designed for beginners. It offers a low-cost way to start building credit without requiring a credit card, loan, or hard credit check. Kikoff is ideal for people who are new to credit or want an affordable first step.
How Kikoff Works
Kikoff provides a small line of credit that you can use to make purchases within the Kikoff platform. You repay what you spend, and those payments are reported to the major credit bureaus. This helps build positive payment history and establish a credit profile.
Why It’s Great for Beginners
- Low cost: Small monthly fee with no high interest
- No hard credit check: Easy to join, even with limited or no credit history
- Simple process: Designed for first-time credit builders
Who Should Use Kikoff
- Individuals with no credit or limited credit history
- Users looking for a low-cost introduction to credit building
- People who want a simple and accessible tool without complex requirements
Key Benefits
- Helps build credit with reported payments
- Affordable monthly cost
- Easy onboarding process
- No hard inquiry on your credit report
Example
A user signs up for Kikoff’s credit builder plan and makes small purchases through the platform. They repay those charges on time, and Kikoff reports the timely payments to the credit bureaus. Over time, this builds a positive credit history and can help increase the user’s credit score.
Kikoff is a practical first step for anyone starting their credit-building journey without a big financial commitment.
Best for: Beginners with no prior credit experience.
6. Chime Credit Builder Card – Best Fee Free Credit Builder Card

What Is the Chime Credit Builder Card?
The Chime Credit Builder Card is a secured credit card offered by Chime that helps you build credit without fees or interest. Unlike traditional credit cards, it doesn’t require a credit check to apply, making it accessible for people with limited or no credit history.
How It Works
- You transfer money from your Chime spending or savings account to your Credit Builder account.
- That amount becomes your credit line.
- When you use the card, payments are made from that secured balance.
- Chime reports your on-time payments to the major credit bureaus (Experian, Equifax, TransUnion), helping improve your credit score.
Why It’s Best for Free Credit Building
- No annual fee
- No interest charges
- No security deposit beyond loading your account
- No credit check to qualify
Who Should Use It
- People with no credit history
- Users with poor credit looking to rebuild
- Anyone wanting a simple, fee-free way to build credit responsibly
Key Benefits
- Builds credit through regular reporting to bureaus
- No hidden fees or interest
- Flexible spending tied to your own funds
- Works like a debit transaction but builds credit like a card
Example
A user transfers $500 to their Chime Credit Builder account. They use the card for everyday purchases and pay back from that balance. Chime reports those on-time payments, which over time contributes to a stronger credit score.
The Chime Credit Builder Card is an excellent, no-cost option for establishing or improving credit using everyday spending and responsible payment behavior.
Best for: People who want a simple, controlled way to build credit.
7. Grow Credit – Best for Subscription Based Credit Building

Grow Credit helps users build credit by paying subscription services through a revolving credit line. Eligible subscriptions include streaming platforms, delivery services, and software tools.
Why Grow Credit Is Unique
- Turns subscriptions into credit activity
- Reports to major credit bureaus
- Offers reward tokens for on time payments
Best for: People with recurring subscription expenses.
8. Credit Sesame – Best for Credit Monitoring With Credit Builder Access

Credit Sesame is a credit management app designed to help users understand, track, and improve their credit over time. While it does not operate as a standalone credit builder loan or card, it plays an important role by giving users visibility into their credit profile and connecting them with products that support credit growth.
Instead of directly reporting payments, Credit Sesame focuses on education and awareness. It provides free access to credit scores, regular updates, and alerts that help users stay informed about changes to their credit file.
For people actively using credit builders, this insight can be just as important as the credit-building activity itself.
The app also offers personalized recommendations based on your credit behavior. These suggestions may include credit cards, loans, or credit builder options that align with your current score and financial situation. This guidance helps reduce guesswork and prevents users from applying for products they’re unlikely to qualify for.
Why Credit Sesame Is Useful
One of the biggest advantages of Credit Sesame is free access to credit scores and reports, allowing users to check their progress without paying monthly fees. Ongoing monitoring and alerts notify you of key changes, such as new accounts, balance shifts, or potential issues that may need attention.
Credit Sesame also stands out for its personalized credit improvement suggestions. Rather than generic advice, the app tailors recommendations based on your actual credit data. This can help users make smarter decisions and avoid common mistakes that slow down progress.
Another valuable feature is access to credit builder and card options. While Credit Sesame does not build credit directly, it helps users discover tools that can. When paired with active credit builders, this creates a more complete and informed credit-building strategy.
How Credit Sesame Fits Into a Credit-Building Plan
Credit Sesame works best as a supporting tool alongside active credit builders like Beem, Self, or Kikoff. These apps handle the reporting of positive payment activity, while Credit Sesame helps you track results, understand score changes, and spot problems early. Together, they provide both action and insight, which is essential for steady improvement.
Best For
Credit Sesame is best for people who want visibility, education, and guidance while building credit with other apps. If you prefer to stay informed, understand why your score changes, and receive tailored recommendations as you work on your credit, Credit Sesame is a strong companion tool.
9. LevelCredit – Best for Rent and Utility Reporting
LevelCredit allows users to report rent and utility payments to credit bureaus, even if the landlord or provider does not report directly.
Benefits
- Adds meaningful payment history
- No need for a new credit account
Best for: Renters with consistent payment habits.
10. Credit Karma – Best for Credit Monitoring and Education

Credit Karma does not build credit directly, but it plays an important supporting role in any credit improvement strategy. While most Credit Builder Apps focus on creating positive payment history, Credit Karma helps you understand how that activity is actually affecting your credit profile. It gives you free access to your credit reports, ongoing alerts, and easy-to-understand explanations that remove the guesswork from credit building.
For anyone using Credit Builder Apps, visibility is essential. Without monitoring, you may not know whether your payments are being reported correctly or if your score is improving as expected. Credit Karma fills that gap by showing changes over time and helping you connect your financial habits to real credit outcomes.
Why Credit Karma Matters
One of Credit Karma’s biggest strengths is its ability to turn complex credit data into clear, actionable insights. Instead of technical language, it explains credit factors in plain terms, making it easier to stay engaged and motivated.
It allows you to track score changes regularly, so you can see how your actions are influencing your credit. This is especially useful when you’re actively using Credit Builder Apps, since progress often happens gradually rather than overnight.
Credit Karma also explains what’s helping or hurting your score, such as payment history, credit usage, and account age, giving you a better sense of where to focus.
Another key benefit is early error detection. Credit Karma helps you spot unfamiliar accounts, incorrect balances, or reporting issues before they cause long-term damage. When combined with Credit Builder Apps, this proactive monitoring helps protect the progress you’re working hard to build.
Best For
Credit Karma is best for monitoring progress alongside credit builder apps and staying informed throughout the credit-building process. It works particularly well as a companion tool, offering clarity, education, and ongoing feedback while your credit builder accounts do the work of reporting positive activity. Used together, these tools create a more confident and informed path toward stronger credit.
Credit Builder Apps Comparison Table
| App Name | Credit Bureaus Reported | Deposit Required | Monthly Cost | Best For |
|---|---|---|---|---|
| Beem Credit Builder Card | Major bureaus | No | Free | Everyday credit building |
| Self | Major bureaus | No | Paid plans | Credit plus savings |
| Experian Boost | Experian | No | Free | Bill payment reporting |
| Credit Strong | All three bureaus | No | Paid plans | Long term rebuilding |
| Kikoff | Experian | No | Low cost | First time credit users |
| Chime Credit Builder | All three bureaus | No | Free | Fee free card users |
| Grow Credit | Major bureaus | No | Free and paid | Subscription payments |
| Credit Sesame | Major bureaus | No | Free and paid | Credit monitoring and builder access |
| LevelCredit | Major bureaus | No | Paid | Rent and utilities |
| Credit Karma | None | No | Free | Monitoring and insights |
How to Choose the Right Credit Builder App
Not all credit builder apps work the same way, and the right choice depends on where you’re starting and what you want to improve.
Some apps focus on adding positive activity to a thin credit file, while others are designed to rebuild trust after missed payments or collections. Understanding your situation first helps you avoid wasted time and frustration.
If You Have No Credit History
If you’re starting from scratch, the goal is simple: get positive activity reported to the credit bureaus as soon as possible. Look for apps that are easy to qualify for and don’t require a high upfront cost.
Apps like Beem, Kikoff, and Experian Boost are strong starting points because they remove many of the traditional barriers to entry. Beem helps you build credit through everyday spending without a security deposit, making it feel more like a regular debit card. Kikoff reports small, manageable monthly payments that help establish a credit record.
Experian Boost works differently by adding eligible bills like utilities and phone payments to your credit profile, which can help create momentum early.
These tools are especially useful for students, young adults, or anyone who has never had a credit card or loan before.
If You Are Rebuilding Credit
If you’ve had late payments, charge-offs, or past financial setbacks, consistency matters more than speed. Rebuilding credit takes patience, and the best apps in this situation are those that create structure and accountability.
Services like Self and Credit Strong use installment-style credit builder accounts. You make fixed monthly payments, and those payments are reported as on-time activity to the credit bureaus.
Over time, this helps offset past negative marks by showing reliable behavior. The predictable payment schedule also makes budgeting easier, reducing the risk of another missed payment.
These options work well for people who want a clear, step-by-step path to improving their credit without relying on revolving balances.
If You Want Everyday Usage
Some people struggle with credit builders because they feel disconnected from daily life. If you want something that fits naturally into your routine, a credit builder card may be the best option.
Credit builder cards like Beem and Chime are designed to be used for regular purchases such as groceries, gas, or subscriptions.
Because you’re using the card the same way you would use a debit card, it’s easier to stay consistent. Payments are handled automatically or tied to funds you already have, which lowers the risk of missed due dates.
This approach is ideal for people who want credit building to happen quietly in the background while they focus on managing their money day to day.
If You Want Extra Visibility
Building credit is easier when you can see what’s happening in real time. Pairing your credit builder with a monitoring tool helps you stay motivated and informed.
Credit Karma is a popular option for tracking your credit score, viewing changes, and spotting potential issues early. It allows you to see how your actions are affecting your credit profile and helps you catch errors before they cause long-term damage. While monitoring tools don’t build credit on their own, they play an important role in helping you stay on track.
Tips to Get the Most Out of Credit Builder Apps
Using a credit builder app correctly matters just as much as choosing the right one. Small habits can make a big difference over time.
Pay Every Bill on Time
Payment history carries the most weight in credit scoring models. Even one late payment can slow your progress or undo months of positive activity. Set up automatic payments whenever possible and treat your credit builder payment like a non-negotiable bill.
Keep Usage Low
If your credit builder involves a revolving account, avoid using too much of the available balance. Keeping usage low shows lenders that you can manage credit responsibly without relying on it too heavily. This habit also makes it easier to pay balances off in full.
Monitor Your Credit Regularly
Check your credit reports often to make sure your payments are being reported correctly. Monitoring also helps you identify errors, unfamiliar accounts, or sudden score drops early, when they’re easier to fix.
Combine Tools Strategically
Using more than one credit-building method can accelerate results when done carefully. For example, pairing a credit builder card with an installment-style account and a monitoring tool can create a well-rounded credit profile.
The key is to avoid overextending yourself. Choose tools you can manage comfortably and focus on consistency rather than speed.
When used responsibly, credit builder apps can turn small, steady actions into meaningful long-term progress.
Final Thoughts
Building credit does not have to be complicated or stressful. Credit builder apps offer structured, low risk ways to establish positive credit habits and improve your financial future.
Among all options available, Beem’s credit builder card stands out for combining ease of use, real world spending, and consistent credit reporting without requiring a security deposit.
By choosing the right credit builder app and staying consistent with payments, you can steadily improve your credit profile and unlock better financial opportunities over time.
People Also Asked About Credit Building Apps
What is the best credit app to build credit?
The best credit app to build credit is Beem. It helps you grow your credit through everyday spending with on-time payments reported to major bureaus, without requiring a traditional security deposit.
Do credit builder apps really work?
Yes, credit builder apps work when used responsibly. They help by reporting positive payment history, which is the most important factor in credit scores, but results take time and consistency.
How to get a 750 CIBIL score?
To reach a 750 CIBIL score, pay all bills on time, keep credit usage low, and avoid frequent loan or card applications. Maintaining this behavior over several months is essential.
What is the best free credit building app?
The best free credit building app is Beem, it lets you build credit through everyday spending with no traditional security deposit, and it reports your on-time activity to major credit bureaus at no cost. Beem combines credit building with practical use, making it a top choice for anyone starting or improving their credit.
Can you build credit for free?
Yes, you can build credit for free. Apps like Beem let you build credit through everyday spending without a traditional security deposit, as long as you make on-time payments. You can also add eligible bills and monitor your credit at no cost to support steady improvement.
How to build a credit score for free?
You can build a credit score for free by using tools that report positive payment activity without requiring a deposit. Apps like Beem help you build credit through everyday spending, while paying all bills on time and keeping balances low supports steady improvement.






